020 8444 5555


Your The ‘Your First Home’ Scheme: A Landlord’s Guide
Headlines claim the new 2.5% deposit scheme will spark a homeownership boom, but retail lending rules tell a different story. Here’s what buy-to-let landlords actually need to know to protect their cash flow.
If you caught the weekend news out of Liverpool, you couldn’t miss the fanfare. Prime Minister Andy Burnham took to the conference stage to unveil what Westminster is pitching as a silver bullet for Generation Rent: the “Your First Home” scheme.
The headline numbers certainly sound dramatic. A wafer-thin 2.5% deposit, a 20% state-backed equity loan, and sweeping new powers for local town halls to seize empty dwellings. The pitch is pure political theatre: rescue locked-out renters without a wealthy “bank of mum and dad”, jump-start housebuilding, and deliver a million-plus new keys.
Predictably, the property forums went into overdrive by Sunday morning. The panic among private landlords was palpable: Will an ultra-low deposit trigger an immediate exodus from the private rented sector? Are we about to face empty flats, tenant shortages, and plummeting yields?
Take a breath. Step away from the conference podiums and look at the hard mathematics.
The private rented sector (PRS) isn’t facing an existential wipeout. In fact, tenant demand is practically guaranteed to stay white-hot. But while your customer base isn’t going anywhere, the day-to-day legal and financial friction of being an independent landlord is quietly turning into a high-stakes endurance test.
Here’s what the policy actually delivers—and how to insulate your rental income before the dust settles.
The Reality Check: Why “Your First Home” Won’t Dent Tenant Demand
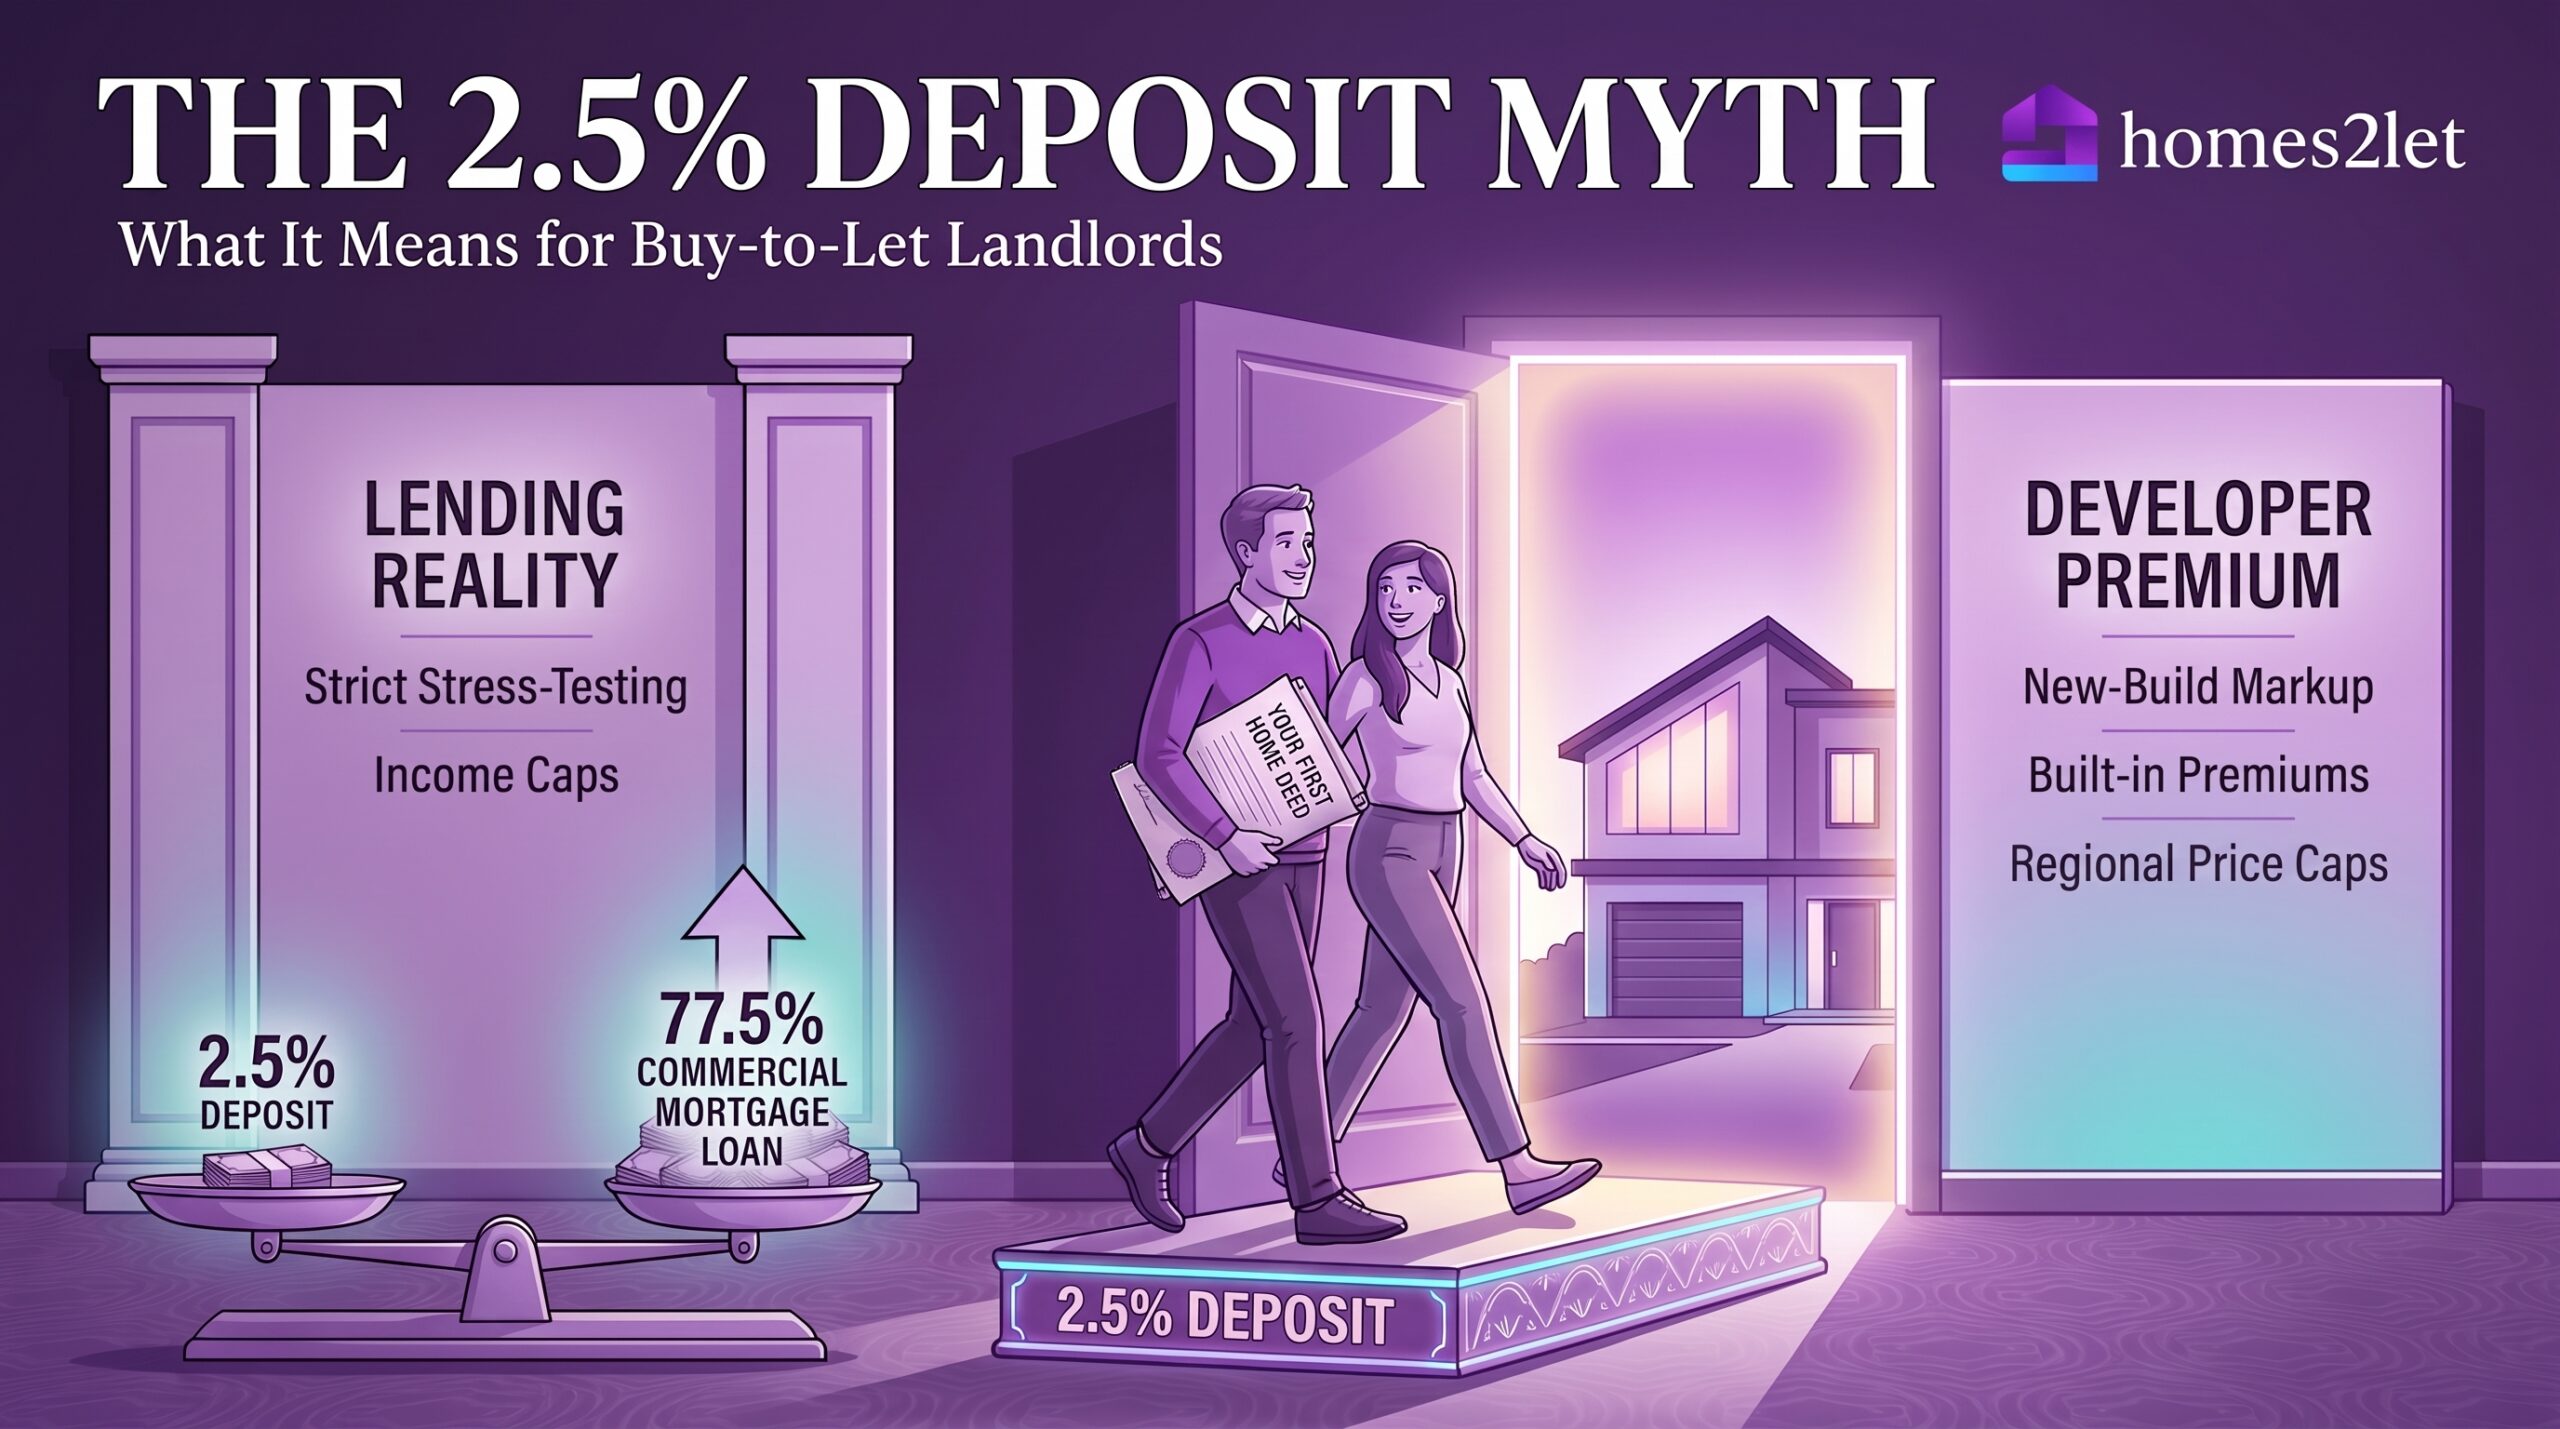
On paper, slashing the upfront hurdle to 2.5% sounds like an open door to homeownership. On a £250,000 starter home, saving £6,250 feels infinitely more achievable than hoarding £25,000 or £30,000 while paying record rents and sky-high energy bills.
Government equity initiatives, however, cannot rewrite retail banking rules. The barriers trip up buyers the moment they speak to a broker:
- The Underwriting Wall: Even with a 20% state loan, the buyer must still fund the remaining 77.5% through a commercial mortgage. With high-street lenders maintaining strict affordability stress-tests—capping borrowing at 4 to 4.5 times gross salary—a couple needs an unblemished, combined income of nearly £50,000 simply to get a look-in. For single earners or those living in pricier pockets of the country, the maths simply falls apart.
- The New-Build Premium Trap: Just like the previous Help to Buy incarnation, this scheme is tied exclusively to new builds. Volume housebuilders are notorious for slapping a 15% to 20% premium on fresh brickwork compared to existing period terraces down the road. That developer markup wipes out the deposit benefit before the buyer even gets the keys cut.
- The Equity Debt Clock: While the initial interest-free window provides short-term breathing room, it’s not free money. It’s government debt tied to the future value of the asset. The moment that grace period expires, monthly outgoings escalate fast—and savvy young buyers know it.
- The Inevitable Caps: The Treasury hasn’t released the fine print yet, but the upcoming Budget will inevitably pin strict household income caps and regional price ceilings to the scheme.
At best, this policy skims off the top 2% of renters who were already on the cusp of buying anyway. For the millions of nurses, teachers, young professionals, and growing families living in our cities, renting remains the only realistic game in town.
The Compulsory Purchase Push: Town Halls Are Circling
The buyer scheme grabbed the front pages, but the real wake-up call for property owners came on Sunday morning. Housing Secretary Angela Rayner confirmed plans to make it drastically simpler for local authorities to seize long-term empty homes—targeting an estimated 300,000 vacant dwellings across England.
Under pressure to hit ambitious delivery targets and drowning in temporary accommodation costs, cash-strapped councils are actively hunting for private stock.
If you have properties sitting vacant between lengthy renovations, caught in probate, or struggling to meet evolving Decent Homes requirements, the spotlight is turning straight onto you. The regulatory net is tightening, and leaving an asset idle or under-managed is rapidly becoming a legal minefield.
The Landlord’s Paradox: Record Demand, Broken Courts
Here is the frustrating contradiction of the modern rental market. Tenant demand has never been more secure. Supply remains structurally choked, building targets routinely slip, and mortgage rates keep prospective buyers renting for longer. Filling a vacant property takes days, not weeks.
Yet running a portfolio the traditional DIY way has never felt riskier.
While Westminster debates deposit thresholds, landlords are left navigating a grinding administrative squeeze:
- The end of Section 21 and the shift toward rigid, evidence-heavy Section 8 claims.
- County courts so completely overloaded that routine possession cases regularly drag on for 9 to 12 months.
- The risk of local authority enforcement and shifting licensing red tape.
Miss one detail on your initial paperwork—an overlooked gas certificate update or a delayed tenancy deposit notice—and an eviction claim gets thrown out by the judge. That puts you straight back to day one of a year-long wait, paying the mortgage out of your own savings while arrears tick upwards.
| Financial Risk Factor | The DIY Landlord Gamble | Homes2Let Guaranteed Rent |
|---|---|---|
| Market Speculation & Voids | Guessing how policy shifts or tenant turnover impact monthly occupancy. | Zero void risk. You are paid 365 days a year, whether the property is tenanted or empty. |
| Missed Rent & Arrears | Immediate cash flow disruption the moment an occupant hits financial trouble. | 100% Guaranteed income, landing on the exact same calendar date every single month. |
| Letting Agent Deductions | Handing over 10%–15% + VAT every month, plus steep renewal and inventory fees. | 0% Commission. No management slices, hidden renewal fees, or surprise markups. |
| Legal & Possession Delays | Facing 12-month county court backlogs, bailiff delays, and spiralling solicitor bills. | Complete operational shielding. We take on all tenant liaison, contracts, and legal admin. |
| Council & Compliance Stress | Juggling Decent Homes mandates, safety paperwork, and empty-home scrutiny. | Total compliance management. Our experienced team handles property upkeep and statutory checks. |
To learn more about what the first-time buyer scheme might mean to you, watch this:
Stop Gambling with Policy Cycles
Politicians will always reach for eye-catching housing schemes when conference season rolls around. Trying to build a long-term investment strategy around whatever headline Westminster produces next month is exhausting.
The most successful landlords aren’t losing sleep over equity loan terms or court backlogs. They simply take default risk and operational friction out of their equation entirely.
Through Homes2Let, you lock in your returns without the traditional buy-to-let headaches:
- Predictable, Guaranteed Income: Your agreed rent arrives every month, without exception. Policy announcements, tenant job changes, and market hiccups won’t touch your cash flow.
- No Commission or Sneaky Surcharges: You keep every penny of your agreed rent. No management percentages, no renewal fees, and no surprise repair invoices.
- True Passive Investment: We manage day-to-day property maintenance, tenant relationships, and compliance requirements from day one. You step away from emergency maintenance calls and legal red tape.
The fundamentals of British property haven’t changed: people need roofs over their heads, and the private rental sector remains vital. What has to change is how much unnecessary risk you take on to stay in it.
Don’t let court delays or policy shifts dictate your financial stability. Speak to the team at Homes2Let today, and find out how our Guaranteed Rent Scheme can protect your portfolio from day one.
Riz is the founder of homes2let and has been in real estate for over twenty years. He has a background in economics and is a real estate developer and buy to let investor.
You can get in touch with Riz via riz@homes-2let.com.
Related Insights
Making Tax Digital for Landlords Explained
Making Tax Digital (MTD) for landlords has been in the pipeline for a while, but soon the time will come for property investors turning over £10,000 a year or more to start reporting tax on a quarterly basis and filing online. The key date is 6 April 2023, which may sound a way off yet, but preparation is crucial. Here’s what you need to know as a landlord about Making Tax Digital so that when the time comes, you’re all set to comply with the new rules.

Buy-to-Let Repossessions Up 5%: Landlord Yield Guide
Buy-to-let repossessions are up 5% as rising mortgage rates and strict RRA regulations squeeze landlord margins. Here is what the latest ONS figures mean for your portfolio—and how to protect your income.
Budget 2021: What it Means for UK Landlords
Today’s budget was much anticipated by many, not least landlords awaiting news on the likes of stamp duty, Capital Gains Tax and financial help for tenants. Here’s the lowdown on what Rishi Sunak’s March budget means for the UK’s buy to let property investors and landlords.