020 8444 5555


Savills’ 2028 Forecast: Hold or Fold?
Savills has pushed a firm UK property market recovery back to 2028. Discover whether you should fiercely protect your current portfolio or ruthlessly liquidate assets to prepare for the 2027 price dip.
Savills’ 2028 Forecast: Hold or Fold?
Let’s be honest about the Autumn Budget hangover. The dust has settled and the reality of new tax burdens is starting to sting. You are probably focused entirely on keeping your portfolio afloat over the next few months. That makes perfect sense. Short-term survival is the priority right now. However, professional investors need to look past the immediate chaos.
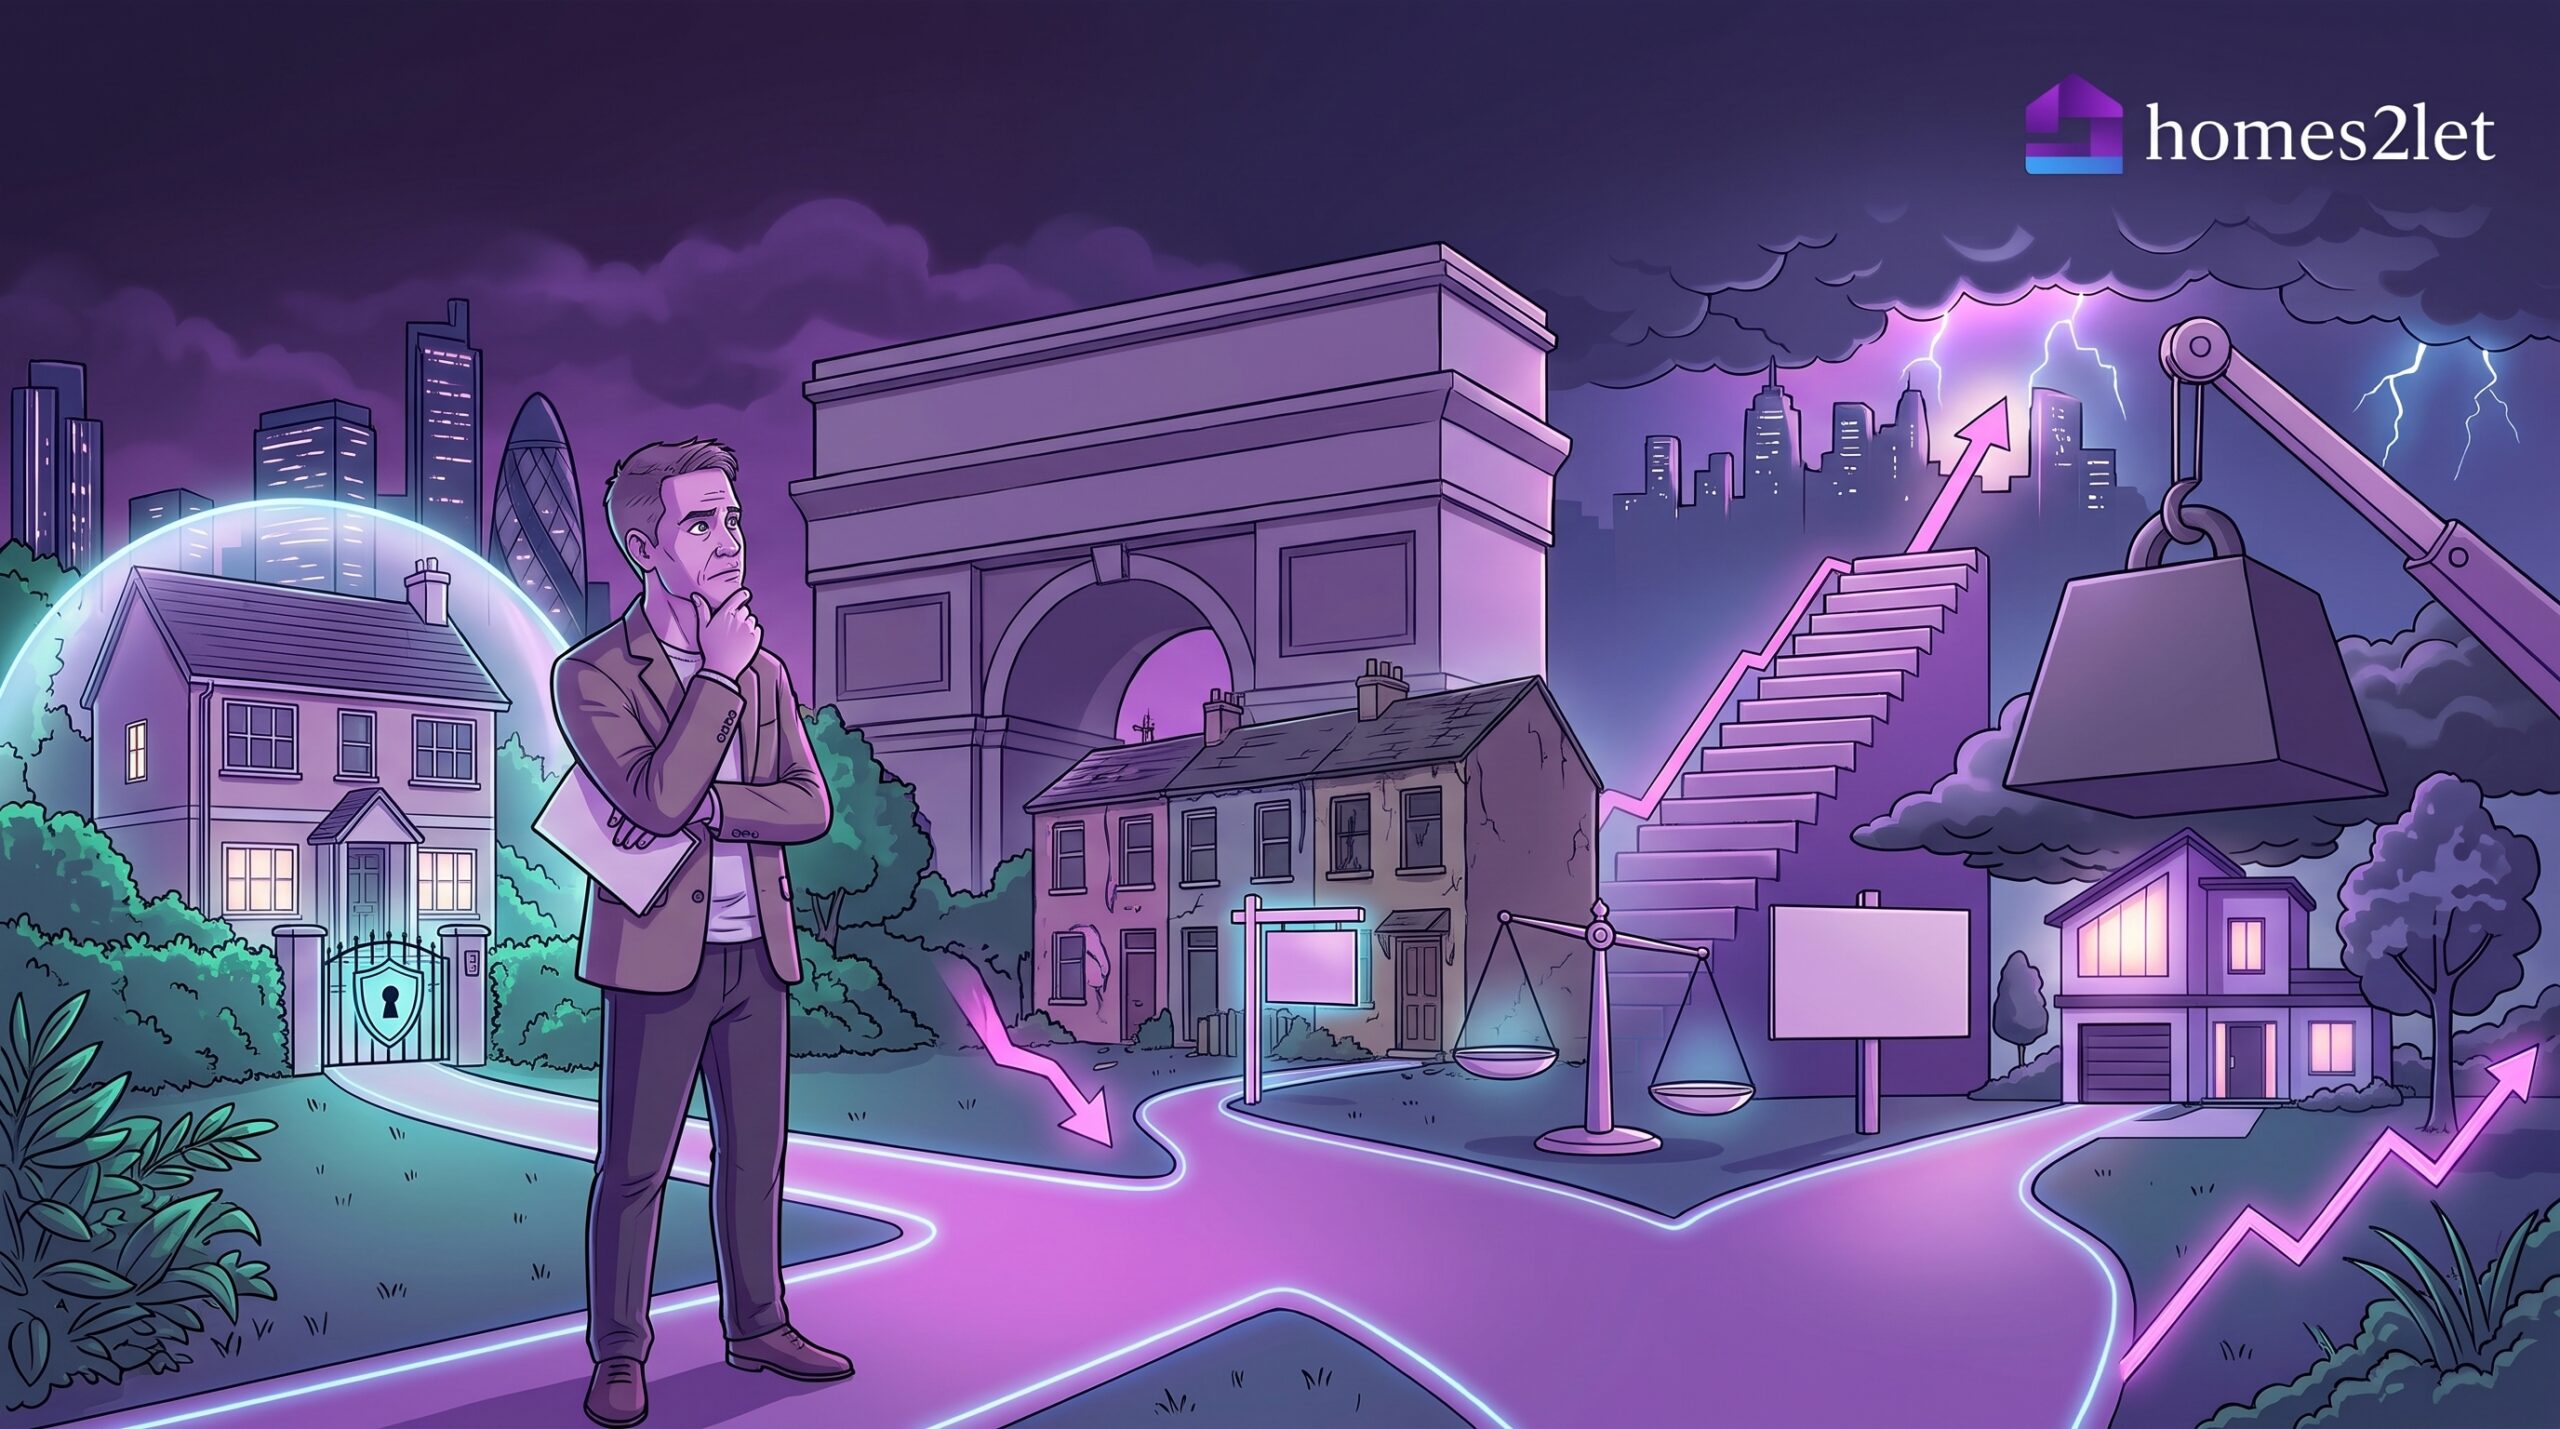
Savills just released their latest housing market forecast and they have pushed a firm market recovery all the way back to 2028. They expect 2026 to be completely stagnant. Following that, they predict a 1.5% drop in average UK house prices throughout 2027, resulting in a total peak-to-trough decline of around 3%. This timeline forces a serious conversation about your portfolio. You have to decide if you are going to fiercely protect your current assets or ruthlessly liquidate them to stockpile cash.
The Mechanics of a Stalled Market
We need to understand exactly why the market is stalling. The Savills forecast hinges on geopolitical instability, stubborn inflation, and punishing borrowing costs. The ongoing conflict in the Middle East has significantly delayed the prospect of meaningful mortgage rate relief. Projections suggest inflation will spike again to around 4.0% by early 2027.
This completely ties the hands of the Bank of England regarding base rate cuts. Mortgage rates remain painfully high in the meantime, and Savills now expects that average mortgage rates will not drop below 5% until early 2028. First-time buyers simply cannot afford to get on the ladder. Because traditional buyers are priced out, capital appreciation is essentially dead for the next 24 months. Relying on your properties to magically increase in value to cover poor rental yields is no longer a viable business plan.

Strategy 1: Active Holding and The Regional Divide
If your properties generate strong yields and house reliable tenants, keeping them is a solid defensive move. You cannot treat this passively. Capital growth will be flat nationally until 2028 at the earliest, but you must also factor in a severe regional divide. Savills points to a “two-speed market,” forecasting a massive 23.3% five-year growth in the North West compared to just 8.1% in London.
Your sole focus must shift to cash flow and regional performance. Recent data shows 75% of landlords plan to raise rents to cover post-Budget costs. You need to ensure your income tracks with inflation. You also have to tread very carefully with good tenants. Pushing rent too high could trigger a move out. Having a property sit empty for two months will instantly wipe out an entire year of potential profit. If your fixed-rate mortgage ends soon, speak to a broker immediately.Lock in a decent rate before inflation drives borrowing costs even higher.
Strategy 2: Ruthless Pruning
Take a hard look at your worst-performing properties. You know the ones. They barely break even each month and require endless maintenance calls. Perhaps they are older terraced houses with an EPC rating of E that will soon demand a £10,000 retrofit.
Now is the exact time to sell them. Holding onto asset liabilities through a stagnant 2026 and a price dip in 2027 will violently drain your resources. Liquidating those properties today lets you extract equity before prices fall further. You will reduce your exposure to expensive debt and free up serious capital.
Strategy 3: The 2027 Buying Window
A depressed market is a goldmine for cash-rich investors. Zoopla data reveals a 7% year-on-year increase in available housing stock. The market is flooded with sellers but devoid of traditional buyers. Tenant demand will only intensify as first-time buyers remain trapped in the rental cycle.
If you free up cash now, you will be in a phenomenal position to buy high-yielding properties at a steep discount during the 2027 dip. You can use the current oversupply of homes to negotiate hard and secure deals well below asking price.When the recovery finally hits in 2028, Savills expects prices to accelerate to 3.5% growth, followed by 5.0% in both 2029 and 2030. Expanding your portfolio at the bottom of the dip positions you perfectly to ride that 15.8% five-year wave.
Want to understand it all better? Watch this:
The Bottom Line
Passive property ownership is dead. The next 24 months will absolutely punish landlords who bury their heads in the sand. You need to take control of your investments today. Review your portfolio this weekend. Run the numbers on every single property you own. Identify your strongest earners and list the ones draining your energy. Making tough decisions now will guarantee you are in the strongest possible financial position when the market finally bounces back in 2028.
Related Insights
Making Tax Digital for Landlords Explained
Making Tax Digital (MTD) for landlords has been in the pipeline for a while, but soon the time will come for property investors turning over £10,000 a year or more to start reporting tax on a quarterly basis and filing online. The key date is 6 April 2023, which may sound a way off yet, but preparation is crucial. Here’s what you need to know as a landlord about Making Tax Digital so that when the time comes, you’re all set to comply with the new rules.
Halifax now lends more on homes with better EPCs
Halifax has thrown down the gauntlet to other mortgage lenders by directly linking borrowing capacity to a property's energy efficiency. Those seeking a mortgage for an energy-guzzling home may find their loan options limited, while buyers of eco-friendly properties could unlock larger loans. This bold move signals a shift in the mortgage landscape, where green credentials are no longer just a 'nice-to-have' but a key factor in affordability.
Paying Tax on Rental Income: Advice for Landlords
Do I pay tax on rental income? It’s a question posed by many would-be or new landlords. It is a good question, but when it comes to taxation of rental income, there is quite a bit to understand. Let’s explore the topic in more detail as we share our experts’ knowledge on the financial side of renting property, together with their top tax tips.